Persuasive Patterns: Influence
Cashless Effect
We spend more when no cash is involved in a transaction

When we pay with credit cards, digital wallets, or contactless taps, spending feels less real. The absence of physical bills and coins disrupts the mental connection between money spent and the value of that money, leading us to spend more freely.
Research found that people spent less on laundry when using cash-operated machines than prepaid cards, and that credit card users consistently spent more than cash users. The pattern holds online too: a smooth checkout – a few clicks, no tangible exchange – makes the purchase feel less significant financially. The physical act of handing over cash creates a “pain of paying” that digital transactions quietly remove.
The study
The Cashless Effect holds surprising power over our spending habits. In a vending machine experiment conducted by researchers at Cornell University. They set up two vending machines side-by-side, each dispensing the same candy bar. One machine only accepted cash, while the other accepted credit cards. The outcome was significant: people were nearly twice as likely to buy a candy bar when they could use credit cards (73% with credit cards vs. 38% with cash). This clever setup demonstrates the Cashless Effect in action.
The physical act of handing over cash makes the cost concrete and encourages restraint. Remove that friction – as with a credit card swipe or digital wallet tap – and the mental connection between spending and its true cost weakens.
Read, D., Loewenstein, G., & Raghubir, R. (2009). The feeling of money: The effect of transaction framing on real-world purchase behavior. Journal of Experimental Psychology: Applied, 15(1), 77-89.
The Cashless Effect is rooted in mental accounting, a concept from behavioral economics. We categorize and track money in mental “accounts,” and physical cash creates a vivid, tangible account – we can see and feel it depleting. Cashless transactions bypass this tangibility. Without the concrete reminder of shrinking cash, our mental accounting becomes fuzzier, and we underestimate the true cost of purchases, especially small ones. The result: looser spending habits, because each transaction feels less significant than it actually is.
Designing products with the Cashless Effect
The core design principle is streamlining the checkout process. The easier and faster it is to pay, the more likely users are to complete transactions. Apple Pay and one-click purchasing capitalize on reducing the “pain of paying.” However, this ease of use is a double-edged sword – convenience shouldn’t come at the expense of mindful spending.
-
Reduce payment friction
Minimize steps between purchase intent and completion. Auto-fill, saved payment methods, and one-tap checkout all lower abandonment rates by removing the moments where the pain of paying might register. -
Reinforce value perception
Since cashless transactions lack the tangible weight of cash, compensate with high-quality product imagery, detailed descriptions, and clear value communication. Help users feel confident that what they’re getting is worth what they’re spending. -
Provide spending visibility
Offer tools that restore some of the awareness that cash naturally provides: spending trackers, budget limits, transaction breakdowns, and post-purchase summaries. These features empower informed decisions alongside cashless convenience. -
Design for responsible patterns
Consider adding friction at strategic points – a confirmation step before large purchases, a spending summary before checkout, or cooldown periods for impulse categories. These small interventions can protect users without undermining the core experience.
Ethical recommendations
Overly aggressive tactics can backfire. Bombarding users with hidden fees, pre-selected high tipping options, or excessively complex pricing structures can erode trust and create a negative user experience. Furthermore, the ease of cashless transactions can mask the true cost of purchases, potentially leading to overspending, particularly for vulnerable populations.
Transparency is paramount. Clearly disclose all costs associated with a purchase, avoiding hidden fees or surprise charges. Offer users control over their spending with features like budgeting tools, spending limits, and clear cashless transaction breakdowns. Additionally, prioritize user education. Equipping users with information about the Cashless Effect empowers them to make informed financial decisions alongside the convenience of cashless transactions.
Real life Cashless Effect examples
Amazon
Amazon has mastered the use of cashless transactions to boost consumer spending. The one-click ordering system minimizes the psychological barriers associated with spending cash, enabling higher average order values. By removing the tangible aspect of cash, consumers are less aware of the expenditure, leading to more frequent and larger purchases.
Spotify
Subscription services like Spotify utilize automatic monthly renewals which are charged directly to credit cards or through digital wallets. This cashless model reduces the friction in transaction processes, lowering the psychological cost of spending and decreasing the likelihood of subscription cancellations due to the convenience and ‘out-of-sight, out-of-mind’ nature of the payments.
Gaming & online betting
Video games and online casinos have integrated in-game currencies and betting credits that users purchase with real money. These credits, which often come in large bundles, mask the actual cost and can lead to greater expenditure. For instance, players may purchase credits to use in digital slot machines or for buying cosmetic items in video games, spending more than they might if direct cash transactions were required.
Trigger Questions
- Can we simplify our checkout process further?
- Do we provide clear value cues for users considering cashless purchases?
- Are all costs transparent and upfront during the buying journey?
- Do users have tools to manage their spending within our cashless system?
- Are we prioritizing convenience without sacrificing user control?
- How can we leverage design to bridge the gap between cashless transactions and informed decision-making?
- How can we integrate cashless options while maintaining trust and security?
Pairings
Cashless Effect + Framing Effect
How offers are framed can significantly influence consumer behavior in conjunction with cashless payments. Presenting prices in a way that highlights the benefits of cashless options, such as smaller, more manageable amounts when paid over time, can encourage higher spending. Frame cashless payments as the smarter, more economical choice, with breakdowns showing smaller periodic payments rather than full prices upfront.
We spend more when no cash is involved in a transaction
The way a fact is presented greatly alters our judgment and decisions
Cashless Effect + Commitment & Consistency + Sunk Cost Bias
People tend to follow through on commitments they’ve made. Offer free trials or subscriptions with cashless billing. Entering your credit card number for a free trial does not cost a thing today, but will when the free trial ends. Once users experience the convenience and establish a routine, they are more likely to continue with cashless payments.
We spend more when no cash is involved in a transaction
We want to appear consistent with our stated beliefs and prior actions
We are hesitant to pull out of something we have put effort into
Cashless Effect + Endowment Effect
We value things we already own more than things we don’t. Combine the Cashless Effect with the Endowment Effect by offering loyalty programs or reward points tied to cashless transactions. Earning rewards for using cashless methods creates a sense of ownership and incentivizes continued use.
We spend more when no cash is involved in a transaction
We value objects more once we feel we own them
Cashless Effect + Rewards
Rewards, especially when paired with cashless transactions, can further minimize the psychological barrier to spending. For example, offering cashback or points when using a card or digital wallet can incentivize users to spend more, leveraging both the Cashless Effect and the Rewards pattern. Design rewards that are automatically applied to cashless purchases to enhance the perceived value and immediacy of rewards, encouraging repeated behavior.
We spend more when no cash is involved in a transaction
Use rewards to encourage continuation of wanted behavior
Cashless Effect + Scarcity Bias
The urgency created by Scarcity can complement the Cashless Effect by nudging consumers to make quick decisions. Cashless transactions reduce the friction in these urgent buying situations, making it easier for users to act before the opportunity disappears. Use time-limited offers or exclusive sales that require immediate, cashless payment to capitalize on this combined effect.
We spend more when no cash is involved in a transaction
We value something more when it is in short supply
Cashless Effect + Loss Aversion
This pairing works by emphasizing what consumers would lose if they do not take advantage of a cashless transaction opportunity. For instance, coupling exclusive discounts for cashless payments with reminders of the extra costs when using cash can be powerful. Clearly communicate the benefits of cashless transactions in terms of savings, convenience, and additional rewards, highlighting what is lost when choosing other payment methods.
We spend more when no cash is involved in a transaction
Our fear of losing motivates us more than the prospect of gaining
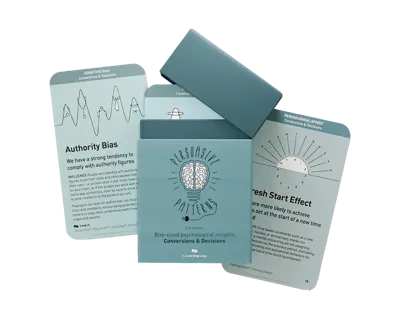
Cashless Effect is one of the cards in this deck
Get this pattern in Persuasive Patterns: Conversions & Decisions.Use physical cards to explore ways to reduce friction and help users make decisions.
$129 · Printed deck + digital edition
Get your deck!- The Cashless Effect by Moneythor Team at Moneythor
- Cashless Effect at The Decision Lab
- Soman, D. (2003). The effect of payment transparency on consumption: Quasi-experiments from the field. Marketing Letters, 14(1), 39-48.
- Hirschman, E. C. (1979). Differences in Consumer Purchase Behavior by Credit Card Payment System. Journal of Consumer Research, 6(1), 58-66.
- Feinberg, R. (n.d.). Credit Cards as Spending Facilitating Stimuli: A conditioning interpretation. Journal of Consumer Research, 13(1), 348-356.
- Raghubir, R., Kumaran, V., & Dlabay, W. R. (2009). The illusion of fungibility: Effects of payment modality on spending behavior. Journal of Consumer Research, 36(6), 853-863.
- Read, D., Loewenstein, G., & Raghubir, R. (2009). The feeling of money: The effect of transaction framing on real-world purchase behavior. Journal of Experimental Psychology: Applied, 15(1), 77-89.
- Thaler, R. H. (1980). Toward a descriptive theory of consumer choice. Journal of Economic Behavior and Organization, 1(1), 39-60.